Buying investment properties can be costly and risky. What makes the most practical sense when you consider costs and risk associated with a project? Buying a property with an existing structure and rehabbing it often makes the most sense. Ground up construction is risky and it requires experience and there are often cost overruns to permitting and issues that arise throughout the process.
There are two options for rehabbing an existing structure.
A) A simple rehab whereby you upgrade the property to a like-new condition by addressing all major systems and maximizing your ARV (after repair value) against like comparable sales in the market. Property selection is key and the competitive landscape for properties is very competitive. The profit margins at exit will be lower so an efficient and accurate exit plan is key.
B) A complex rehab, where you take an existing structure and add square foot living space. In the process, you may very well be eliminating functional obsolescence and creating a much more desirable and valuable property. This option requires more experience and vision but often carries a higher profit margin at the exit.
Regardless of your choice of a simple or complex rehab, how do most people address the acquisition and rehab/construction phase of a project? Most people will seek property based hard money loans for these types of projects. These loans are usually offered for a 12-month term with higher interest rates and points. If you are an efficient operator and have a crew or reliable contractors and your scope of work is realistic, you can consistently profit at the exit. The problem we see with many clients that call us to ask for a hard money bailout or a permanent loan to replace hard money is they didn’t have an accurate plan from the start that truly reflected the costs and the hard money financing. This puts them in a position where they are facing late fees and often do not have the proper equity position to satisfy the requirements of a 30-year permanent loan. This means they are stuck, and the high cost of the hard money loan puts them at risk. To solve this dilemma, you either have to sell the property or come up with the cash to meet the requirements of the permanent loan so you can pay off the hard money lender. This is a very common situation. The risk is if you do nothing, you can also lose your property to the hard money lender.
We also offer hard money loans from our portfolio. There is no foreclosure. You sign a deed in lieu up front. The only difference between us and other hard money lenders is that we will not lend you money on a project unless we test your scope of work and plan. If it is not realistic based on the cost estimate to improve the property to equate to the comps then we will not lend you the money. I can tell you that is not the character I have seen from many hard money lenders. Having said that, if you can avoid hard money with a lower cost and risk option, you should consider it from the start.
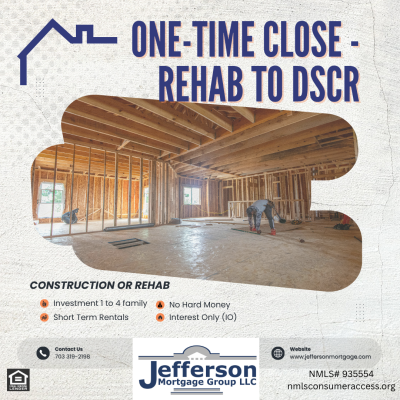
An option to avoid the risk and costs associated with Hard Money is with a one-time closing option. You provide your scope of work and draw schedule requests up front. The loan approval consists of the rehab/construction phase and once complete, immediately modifies to the permanent 30-year fixed DSCR loan. You will never have to worry about being stuck in a hard money loan or being forced to prematurely sell your property. This is the safest lower cost option for BRRRR investors and rehabbers that want to build their rental real estate portfolios.
What are the mechanics of the one-time close loan? The rehab/construction period is usually the first 12 months. During this time, you pay Interest Only (IO) payments on the balance drawn on the loan as the property is improved. The rates and costs are much lower than traditional hard money. Once the improvement phase has been completed, there is a simple note modification that converts the loan into a fully amortized fixed rate DSCR loan at the current market rate. There is no additional qualifying. You automatically receive the modification. Remember the DSCR loan is a property-based loan. From the original review point, the debt coverage ratio has been assessed to determine the project meets eligibility. What does this mean in layman’s terms? This means the property cash flows and it’s a good investment decision based on loan size and the properties marketable rent characteristics.
In summary, the most important aspect of renovating or constructing a property is accuracy within the scope of the project and the costs to the exit point or conversion to income producing property. Hard money lending is a tool that works but with costs and risks. When considering a project, it is recommended that you carefully assess these items. A one-time Rehab/construction to DSCR closing can eliminate this associated risk.
George H. Omilan
President-CEO - NMLS# 873983
Jefferson Mortgage Group LLC
Questions/Comments encouraged.
Comments
Comment Submitted!